Direct answer: AI pricing has iterated from seat-based to usage-based to hybrid and outcome-based models three times in three years. ASC 606 and IFRS 15 both accommodate variable consideration in principle, but the billing, ERP, and revenue recognition systems built for fixed-fee SaaS were never designed to apply it consistently at scale. That gap, not the accounting standards themselves, is the operational risk finance teams are underestimating.
For most of the SaaS era, seat-based pricing was a reasonable proxy for value. Licenses were predictable, billing was straightforward, and revenue recognition followed a relatively clean path.
AI products are disrupting that logic.
When value is delivered through tokens consumed, actions completed, or outcomes achieved rather than named users, a flat per-seat fee stops reflecting commercial reality. Product and pricing teams have responded quickly. Finance infrastructure, in most organizations, has not.
This article maps where AI monetization is heading in 2026 and why the systems behind revenue recognition are becoming the next operational bottleneck, even before most finance teams have fully registered the problem.
Why Is AI Monetization Outpacing Revenue Recognition?
Pricing models are changing faster than the systems built to account for them, and that gap is now wide enough to matter operationally. Seat-based pricing worked when software usage was predictable. AI pricing tracks tokens, actions, and outcomes instead, and most finance stacks were built for the old model.
What Do the Latest AI Monetization Trends Show?
The pace of change here is not incremental. By the end of 2025, 79 companies had adopted usage-based AI pricing models, more than double the number from 2024. That kind of acceleration suggests the shift has moved well past early experimentation into broader commercial adoption.
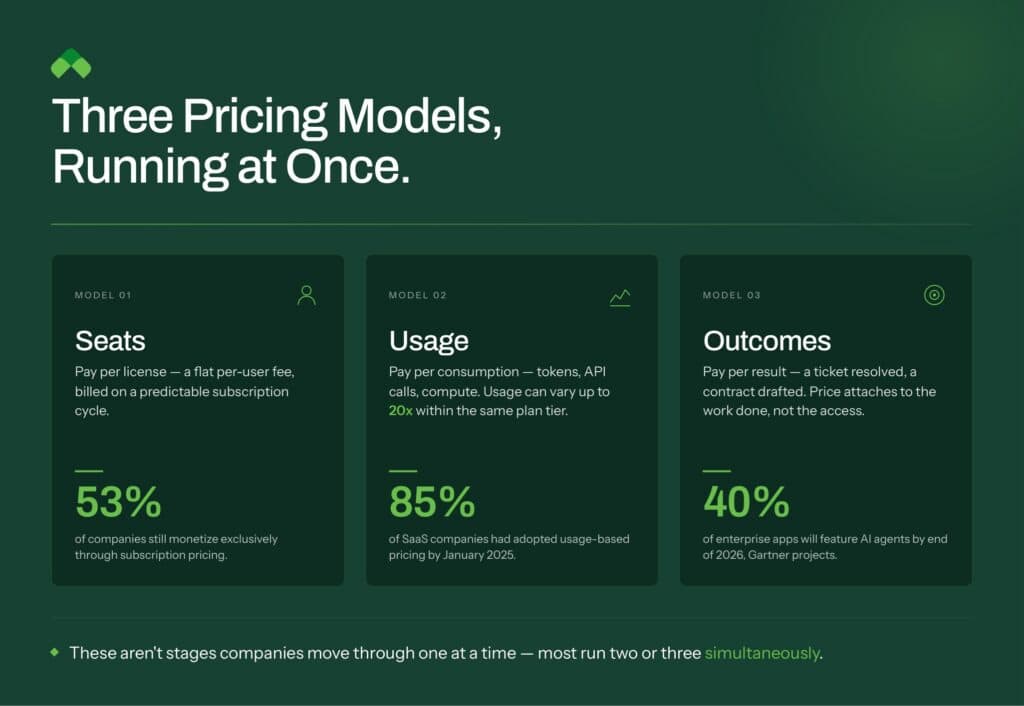
The underlying trend has been building for years. 85% of SaaS companies had adopted usage-based pricing in some form by January 2025, per Metronome’s State of Usage-Based Pricing 2025 Report. AI pricing is now accelerating on top of an already-established structural shift, which is part of why the pace feels compressed.
What makes the current moment distinct is the instability within the shift itself. Companies that charge for AI usage are rarely settling on their first model. Most iterate at least once or twice before landing somewhere that sticks, and the market has not converged on a standard. Pricing teams are still iterating actively, and the models they are iterating toward are meaningfully more complex than what came before.
Most finance teams are treating this as a product decision. It isn’t just a pricing exercise. Pricing changes flow downstream into quoting logic, invoicing, and revenue measurement, and finance teams that wait for the pricing model to “settle” before building the systems to handle it are going to find out the hard way that it never settles. There is no stable end state coming.
The operational risk is not that usage-based pricing is inherently unmanageable. It is that frequent pricing model changes, layered on top of existing subscription infrastructure, create reconciliation pressure that compounds over time. A model that changes twice in a year may be commercially defensible. It still creates downstream exceptions that someone has to resolve manually if the underlying systems were not built to absorb that kind of variability.
Seat-Based Pricing Is Breaking Under AI
Seat-based pricing assumed even usage. AI doesn’t work that way. Consumption under AI products is deeply uneven, sometimes varying by as much as 20 times within the same plan tier. One user may interact with an AI feature occasionally, while another drives substantial model activity and infrastructure cost, all under the same license fee.
From a commercial standpoint, that unevenness cuts both ways. Low-usage customers feel like they’re subsidizing infrastructure they barely touch. High-usage customers represent a margin risk the pricing model was never built to price in.
This is not a failure of seat-based pricing as a concept. It worked well when software usage was relatively uniform across a user base. AI products, by their nature, are consumed unevenly. The pricing model that made sense for a CRM license does not translate cleanly to an AI assistant or an agentic workflow tool.
Hybrid Pricing Models Are Gaining Ground
Hybrid models are winning, but not for the reason most people assume. The market is not simply replacing subscriptions with consumption. It is layering new monetization logic onto existing recurring models. Hybrid structures, typically a subscription floor combined with usage-based expansion, are where many mature companies are landing.
The commercial rationale is clear enough on paper: Stripe’s research found 21% higher median growth for hybrid models compared with pure subscription or pure usage approaches. But growth numbers like that get repeated in decks without anyone asking whether the comparison is fair. Hybrid models are disproportionately being adopted by more mature, better-resourced companies in the first place, so some of that growth premium may be selection, not the pricing model doing the work.
For finance readers, the more useful takeaway isn’t the growth number. It’s that hybrid pricing isn’t a clean replacement for subscriptions. It’s an additive layer of complexity stacked on top of the contract structures finance teams already have to track.
Usage-Based Pricing Makes Forecasting Harder
The value-alignment benefits of usage-based pricing come with a real trade-off in predictability. When price tracks consumption, and consumption is variable, forecasting becomes harder for everyone in the chain, including the finance teams responsible for revenue planning and gross margin analysis.
For organizations selling AI products, the forecasting challenge runs in both directions. On the buy side, variable AI tool costs are harder to budget. On the sell side, variable revenue from usage-based customers introduces more uncertainty into revenue projections, particularly when usage patterns are still maturing and historical data is limited.
How Much Are Companies Actually Spending on AI-Native Applications?
The spend is real. The universality isn’t. Both things are true at once. The dollar exposure is becoming material: organizations spent an average of $1.2 million on AI-native applications in 2026, a 108% year-over-year increase, per Zylo’s 2026 SaaS Management Index. That kind of spend growth, combined with pricing models that are still actively evolving, creates real exposure for finance teams that have not yet built the controls to manage it.
That said, 53% of companies still monetize exclusively through subscription models, and per-seat pricing still dominates across the broader market. That gap is closing fast, and the companies still treating full AI monetization as an edge case are the ones that will be scrambling when it isn’t. The 53% still on pure subscriptions today isn’t evidence this is overhyped. It’s more likely a sign that a lot of finance teams are going to hit this wall later than their pricing teams expect, and with less runway to prepare than they think they have.
Where Is AI Monetization Headed?
Usage, hybrid, and outcome-based pricing aren’t stages a company moves through one at a time. They’re running side by side right now, often inside the same contract.
Is Outcome-Based Pricing Already Happening, or Still Coming?
Outcome-based pricing is already here, alongside everything else. Outcome-based pricing measures results instead of consumption: the customer pays for a ticket resolved, a contract drafted, or a meeting booked, not for the compute that produced it. That’s already showing up across the market, not a future stage.
Gartner projects that 40% of enterprise applications will feature AI agents by the end of 2026, up from under 5% today, and that shift is already reshaping how vendors price. As AI products get more agentic, buyers increasingly expect to pay for what the agent accomplishes, not the infrastructure it consumes to get there.
Each Pricing Iteration Redefines What ‘Value’ Means
Seats were simple to administer. Usage got closer to the truth but brought variability with it. Outcome-based pricing tries to skip straight to paying for results, which sounds great until you’re the one who has to define, dispute, and audit what counts as a “result.”
In practice, the model that worked at $1 million ARR often becomes less effective at $10 million ARR, when customer behavior is more visible, infrastructure costs are more significant, and the gap between what customers pay and what they receive becomes harder to ignore. The progression is not a straight line. Some businesses will keep subscriptions at the core while redefining what a seat includes. Others will move more aggressively toward pure consumption or outcome structures. This space is still evolving quickly, and best practices are still being written.
The Systems Behind Revenue Recognition Are Falling Behind
Is Usage-Based Revenue Recognition Harder Because of the Accounting or the Systems?
Revenue recognition frameworks were operationalized in most companies around fixed fees, stable contract terms, and relatively predictable billing patterns. Both ASC 606 and IFRS 15 accommodate variable consideration on paper. Accommodating it consistently, at scale, with an audit trail that holds up, is a different problem entirely, and it’s the part almost nobody talks about when they cite the standards as though the standard itself solves anything.
Usage-based and hybrid structures introduce timing questions and estimation requirements that don’t exist in a straightforward subscription model, on top of pulling consumption data from systems that were never designed to talk to the general ledger. SSP allocation gets harder to apply consistently. Deferred revenue rollforward gets harder to reconcile when the underlying contract terms shift mid-period. That is manageable with the right infrastructure. It is not manageable with the systems most companies built for a simpler pricing world.
The mechanics of how variable consideration applies to these structures, and what that means for revenue schedules, allocation, and close processes, is a longer conversation. The short version is that pricing has iterated three times in three years. From seats to usage to outcomes, revenue models have changed, but most systems built to support revenue recognition, designed for a world of fixed fees and predictable terms, haven’t kept pace. RightRev was built for this shift from the start.
When Does the Revenue Recognition Gap Actually Show Up?
The gap is not primarily a technical accounting question. It is an infrastructure and operational readiness question. Pricing teams can iterate quickly because pricing changes are largely a product and commercial decision. Revenue recognition changes require system configuration, data pipeline adjustments, control documentation, and often audit-level scrutiny. Those cycles move at different speeds, and nobody’s incentivized to slow the faster one down to match the slower one.
That gap does not always surface immediately. It tends to appear later: in manual workarounds that extend month-end close, in forecast variance that cannot be cleanly explained, in billing exceptions that require individual resolution, or in audit questions about how variable consideration was estimated and constrained. By the time those symptoms appear, the pricing model has often already moved again.
What Determines Who Wins This Transition
The commercial logic behind usage-based and outcome-based AI pricing is sound. Aligning price to value is the right direction. The businesses that navigate this transition most effectively, though, will not necessarily be the ones that designed the most sophisticated pricing structure. They’ll be the ones whose finance stack can actually keep up with it: data that flows cleanly, recognition logic that holds up to an auditor, and enough operational slack to absorb the next pricing change without losing control of the close.
RightRev’s Revi Architect helps finance teams design and test recognition logic against a shifting pricing model before it hits production, so the audit trail holds up when the contract terms change mid-period. Read more here
MGI Research’s 2025 Automated Revenue Management Top 30 Buyer’s Guide rates RightRev an A, with a Positive analyst outlook and the second-highest Product Score of the 16 suppliers rated. RightRev’s overall score increased more than any other rated supplier in this year’s edition, and MGI names it a fit for organizations running revenue automation needs from straightforward rev rec through the most complex, high-volume requirements, natively within Salesforce and Snowflake or off-platform. At Epicor, RightRev’s platform replaced a manual process of allocations, contract modifications, and SSP analysis with automated processing of nearly a million revenue contract lines in minutes.
If your current billing, ERP, and revenue workflows were built for a subscription world, it is worth assessing how much of that infrastructure will hold as your pricing model evolves. RightRev’s Revenue Complexity Assessment is a practical starting point for that evaluation, an 11-question diagnostic that helps finance teams identify where the gaps are before they show up in the numbers.
Frequently Asked Questions
What is consumption-based pricing and how is it different from subscription pricing?
Consumption-based pricing charges customers based on actual usage of a product or service, such as API calls, compute hours, or data volume. Subscription pricing charges a fixed recurring fee for access regardless of usage. From a revenue recognition standpoint, consumption models require variable consideration treatment, whereas subscriptions are typically recognized ratably.
What are the best revenue recognition software vendors for AI Products?
AI products introduce unique revenue recognition challenges, token-based consumption, prepaid credit drawdowns, and hybrid pricing models that don’t fit traditional subscription frameworks. Look for platforms that handle variable consideration and usage-based recognition under ASC 606 at scale, rather than legacy tools designed for simpler seat-based models. RightRev is a strong fit for AI companies navigating this complexity, with flexible, policy-driven automation built for consumption-based and hybrid contracts.
What should CFOs know about revenue recognition automation before evaluating software?
CFOs should understand that revenue recognition automation is not just a compliance tool but a strategic finance investment. The right platform reduces close cycle time, improves audit readiness, enables real-time revenue visibility, and scales with business complexity. The evaluation should include total cost of ownership, integration requirements, and the ability to support new business models like usage-based pricing.